

By Rober Miller, Portfolio Manager, NAOS Asset Management
While reading a hard-copy newspaper recently, I noticed a front-page advertisement wrap that caught my eye. No, it wasn’t the seemingly frequent Harvey Norman one, which often covers the newspaper; rather, it was an advertisement for Riedel wine glasses. To be upfront, I’m not looking to buy high-end crystal stemware, nor would I ever have given a second thought to such an ad, but I found a single line in the text quite fascinating. While it is not wise to believe everything marketed to consumers, the advertisement stated that Riedel is an 11th-generation family company.
For those interested, the business was founded in Bohemia (now the Czech Republic) in 1756 by Johann Leopold Riedel. It survived World War II and was essentially re-founded in Kufstein, Austria, in 1956; in 1973, it invented the grape-specific wine glass that the rest of the industry has copied ever since. Today it is run by the 11th-generation Maximilian Riedel, with his father, Georg, still involved in the business.
It got me thinking. Firstly, this company has been around longer than when Captain Cook sailed to these shores, but also, how does a company survive eleven handovers from one generation to the next, each one an opportunity for things to go wrong? What other companies have managed this feat, which have fallen over along the way, and more importantly for investors, what separates the two groups?
The Odds Are Not in Your Favour
There is a very well-known saying when it comes to family businesses: the first generation builds it, the second maintains it, and the third generation destroys it. The most-quoted statistic on the topic comes from a 1980s study by Professor John Ward of 200 family-owned manufacturing businesses in the US state of Illinois between 1924 and 1984. Roughly 30% of family firms make it to the second generation, 13% to the third, and a mere 3% to the fourth generation and beyond.
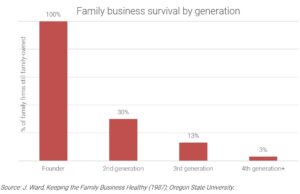
Source: J. Ward, Keeping the Family Business Healthy (1987); Oregon State University.
With this data, there are a few big caveats with significant selection (and survivorship) bias: it is single-geography, single-industry, single-era focused, and a family that sells a thriving business at a good price is counted as a ‘failure’. Nonetheless, the general direction of travel can probably be relied upon to a certain degree. Any company which makes it through to generation #5 would be in rarefied air.
The Global Landscape
On the topic of longevity, Japan is always near the top of that list across many facets. Think of the Blue Zones around the world (specific regions where an exceptionally high number of people live to the age of 100), and the island of Okinawa in Japan is on that list. When it comes to companies, a Bank of Korea study identified 5,586 companies worldwide that were more than 200 years old, and 56% of them were Japanese. Germany was a distant second (side note – data in Europe is more fragmented without a quality ‘clean cohort’ of data).
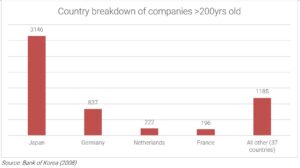
Source: Bank of Korea (2008)
The most famous of the Japanese ‘shinise’ (long-established companies) was Kongō Gumi, a temple builder founded in 578 AD and run by 40 generations of the Kongō family. It is widely regarded as the world’s oldest continuously operating company. Interestingly, bloodline was never the deciding factor in who would lead the company. The family routinely adopted the most capable son-in-law, who took the Kongō name and the keys to the business. What finally ended a 1,400-year run in 2006 was not a lack of heirs; it was ~¥4 billion of debt and competition from large construction companies as concrete replaced timber. The business now lives on as a subsidiary of Japanese listed company Takamatsu Construction Group (TYO: 1762).
It would probably come as no surprise that most of the world’s oldest family companies are privately held, rather than being publicly listed. Something I learnt when putting this article together is that there is an association called The Hénokiens, which is open only to companies more than 200 years old in which the founding family still owns more than half the capital. There are 56 members of this association and stating what may be obvious, none of them are Australian.
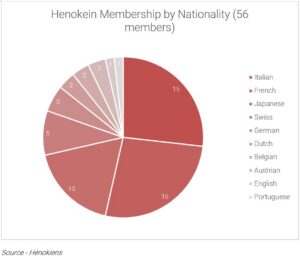
Source – Hénokiens
That said, a handful of genuinely multi-generational businesses have managed to combine family control with a stock exchange listing:
- Merck KGaA (ETR: MRK) – founded as a pharmacy in Darmstadt, Germany in 1668. The Merck family is now in its 13th generation and retains ~70% of the business through a partnership structure.
- Hermès International SCA (EPA: RMS) – founded in 1837. Axel Dumas, a sixth-generation family member, is CEO, and the family controls roughly two-thirds of the shares, locked up in a family holding company after LVMH Moët Hennessy Louis Vuitton SE (EPA: MC) quietly built a stake in 2010.
- Molson Coors Beverage Co (NYSE: TAP) – the Molson brewery was founded in Montreal, Canada, in 1786, and the seventh generation sits on the board today.
- Swire Pacific Ltd (HK: 0019) – the conglomerate was founded in Liverpool, England in 1816 and now led by the sixth generation of the Swire family.
The Domestic Landscape
Australia is a young country, so, on a relative basis, we need to lower the bar when compared to global peers. Starting with Washington H. Soul Pattinson & Co Ltd (ASX: SOL). Caleb Soul opened a pharmacy on Pitt Street in 1872, Lewy Pattinson opened his in Balmain in 1886, and the merged business listed on the Sydney Stock Exchange on 21 January 1903 at £1/share. SOL’s global distinction is its status as a Dividend Aristocrat. It has paid a dividend every year since listing and has increased that dividend for 27 consecutive years.
Away from the ASX, South Australia appears to be the main source of longevity when it comes to generational companies in Australia. The list includes:
- Beerenberg Family Farm (the maker of the well-known sauces and jams was started in 1839 and is now into the 6th generation of the Paech family);
- Yalumba (1849, the 5th and 6th generations involved in the business with chairman Robert Hill-Smith a 5th generation family member); and
- Coopers Brewery (1862, now in its sixth generation of family ownership).
Other notable examples, such as Fairfax, remained in family ownership for 146 years until 1990, whilst McWilliam’s Wines, founded in 1877 and run by six generations, entered administration in January 2020.
So, What Tangible & Intangible Factors Make Them Stand the Test of Time?
Looking across the survivors and the failures, four things stand out to us:
- A conservative balance sheet – For any company, debt is a common thread in business failure, and these generational family companies are certainly no different. Nearly every company mentioned in this article that has ceased after an amazing stint failed because of leverage (i.e. Kongō Gumi, Fairfax, McWilliam’s Wines). Surveys of Japanese ‘shinise’ companies suggest around a quarter hold enough cash reserves to fund two years of operations. Multi-generational companies fund growth out of cash flow, not borrowings.
- Caretakers, not Dictators – Each generation sees itself as a custodian for the next, which naturally stretches the time horizon out to decades rather than quarters. If such a mindset is adopted as a foundational principle, then one can only assume decisions are made in the best interests of the long term, not the short term.
- Evolving and avoiding a ‘Kodak moment’ – Riedel still makes glass, but it reinvented itself to create the modern-day wine glass. Nintendo started as a playing-card maker in 1889, and look where it has evolved to with technological advancements over time. In Australia, SOL went from pharmacies to a diversified investment conglomerate. Having the ability and foresight to pivot and/or adapt to changing industry tailwinds would underpin a lot of these companies’ longevity.
- Somewhat avoiding birthrights through meritocracy – The oldest company on this list Kongō Gumi adopted its heirs. Many of the listed survivors have a family chairman and a professional, non-family CEO, which may be a critical factor in operational success and in being able to have a level of independence from different viewpoints of family members.
The NAOS Perspective
In a time when equity markets are increasingly focused on the here and now, being able to focus on a longer-term investment horizon can be seen as a competitive advantage. At NAOS, one of our investment principles is to look at companies through at least a 5-year investment horizon. In some respects, companies are similar to humans; they are living and breathing entities, and growth can be years in the making rather than through overnight success.
In looking at these generational companies, what we do find useful is that the behaviours of companies that have survived 150 years look remarkably like the attributes we look for in an emerging company today, including:
- Conservative balance sheets
- Healthy free cash flow which can be reinvested;
- A consistent approach to capital allocation; and
- Management teams that think and act like owners and are stewards of shareholder funds.
Credit Suisse had a long-running ‘Family 1000’ research paper which found that family-controlled listed companies outperformed the broader market by ~370 bps p.a. from 2006 to 2020. In addition, these companies were far more likely to reduce net debt than their peers. Limited research on such companies (again noting significant survivorship bias) suggests these attributes have historically produced outperformance.
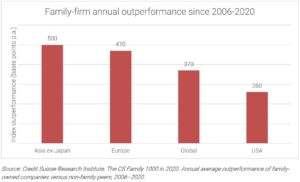
Source: Credit Suisse Research Institute, The CS Family 1000 in 2020. Annual average outperformance of family-owned companies versus non-family peers, 2006–2020.
“If we think long term, we can accomplish things that we couldn’t otherwise accomplish”
Jeff Bezos, Founder, Amazon.com Inc (NDQ: AMZN)
Important Information: This material has been prepared by NAOS Asset Management Pty Ltd (ABN 23 107 624 126, AFSL 273529 and is provided for general information purposes only and must not be construed as investment advice. It does not take into account the investment objectives, financial situation or needs of any particular investor. Before making an investment decision, investors should consider obtaining professional investment advice that is tailored to their specific circumstances.